Have a Question About Mortgages? Ask Steph!
604-575-2710

The Advantage of Choice
Hi, I’m Stephanie Barritt, a mortgage professional serving clients in the lower mainland from my office in Surrey BC. Choosing the right mortgage is a big decision. Finding the right mortgage is a powerful tool to help you achieve your financial goals, while getting stuck with a bad one has the potential to cost you a lot of money.
So with so many mortgage choices and ongoing decisions to make, how do you know you are making the right choice for you? You need an independent mortgage broker to help guide you! A banker works for the bank, paid by the bank to make money for the bank. As a mortgage broker I can represent you to several different lending institutions who offer a wide choice of products.
The combination of unbiased advice, access to more products, and the fact that my business that is built on customer service and client education means that when you work with me, you can be assured that your needs are being put first. And in most cases, my services come at no cost to you! Regardless of where you are in the mortgage process,
I can help! Ask me about mortgages anytime!
Everything you need, all in one place
As a trusted mortgage provider, I can help you with these services.
Testimonials
HIGHLY RECOMMENDED
Stephanie came recommended to me and she did a great job with our mortgage. She’s the kind of person that really fights to find the best product to suit our needs and she puts long-term service over any other considerations. I highly recommend her for any mortgage or other real estate finance needs.
Stephanie came recommended to me and she did a great job with our mortgage. She’s the kind of person that really fights to find the best product to suit our needs and she puts long-term service over any other considerations. I highly recommend her for any mortgage or other real estate finance needs.
Peter Crisp
FAST AND PROFESSIONAL
I use Stephanie Barritt almost exclusively for my real estate clients because she is fast, professional, and if there’s any difficulty, she can handle it! I wouldn’t hesitate to recommend her!
I use Stephanie Barritt almost exclusively for my real estate clients because she is fast, professional, and if there’s any difficulty, she can handle it! I wouldn’t hesitate to recommend her!
Dianne Moscrip, ReMax Advantage Realty
EXCEPTIONAL PRODUCT KNOWLEDGE
Stephanie has done such a great job for many of my clients. On more than one occasion, she has gotten my clients great mortgages when other brokers could not find a way. Her exceptional product knowledge is second to none in my opinion and I look forward to sending her more business, as I know that she can do for my clients, what no one else can.
Stephanie has done such a great job for many of my clients. On more than one occasion, she has gotten my clients great mortgages when other brokers could not find a way. Her exceptional product knowledge is second to none in my opinion and I look forward to sending her more business, as I know that she can do for my clients, what no one else can.
Eldon Whalen
PROFESSIONAL AND FRIENDLY SERVICE - HIGHLY RECOMMENDED!
As first time buyers we were very unsure of what we were doing, but Steph provided us with all the support and help we needed. Answering any questions we had, whilst being very patient and lovely in the process. Alongside her assistant Jennifer, Steph offered us a smooth end to end service, finding us a great deal and moved things along quickly for us when needed. We will definitely be returning customers when the time comes!
As first time buyers we were very unsure of what we were doing, but Steph provided us with all the support and help we needed. Answering any questions we had, whilst being very patient and lovely in the process. Alongside her assistant Jennifer, Steph offered us a smooth end to end service, finding us a great deal and moved things along quickly for us when needed. We will definitely be returning customers when the time comes!
Marie Norton and Andrew Mills
EXCEPTIONAL SERVICE
Stephanie was referred to us by our real estate agent. Everything happened so fast and only in a matter of days, Stephanie was able to help us as we didn’t have much time to remove conditions and our financing wasn’t approved yet. Stephanie along with the help and collaboration of Jennifer were able to help us out and get everything sorted in the very short time we had and by help I mean gather all the required documents (this can become a tedious task), and get me approved within a matter of days only.
It was a very stressful time and I don’t know how I would have done it without them. The quality of service provided was exceptional and we were so relieved that we were able to remove conditions on time, with my financing being fully approved and complete. Stephanie and Jennifer remained very professional throughout the whole process while being very friendly and keeping stress levels as low as possible. I would strongly recommend working with them, especially being a first time buyer, it was very important that I worked with someone who could answer many annoying questions and they both always responded to me so quickly and every time with a smile, which as a customer made me feel very comfortable and that really helped reduced my stress levels too.
In terms of negotiating the mortgage details, I will admit that after looking around, Stephanie was also able to provide me with the best interest rate available! Without asking, I was informed that a better rate was negotiated for me (what better can one ask!).
When it’s time to redo the paperwork, I can guarantee that I will be a returning customer. My experience applying for a mortgage for the very first time was very smooth, very easy and extremely professional, allowing for the best experience any first time home owner could ask for 🙂 Thank you Stephanie and Jennifer
C. Ramdoyal
Some of My Lenders
I Keep My Blog Updated So You Can Stay Informed

On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
Mortgage Options During Divorce or Separation: What You Should Know If you’re going through—or considering—a divorce or separation, you may not realize that there are mortgage solutions specifically designed to help one party keep the home . For many people, the family home is their largest asset and where most of their equity is tied up. In situations like this, a spousal buyout program can allow one person to refinance the property and buy out the other party’s share—often up to 95% of the home’s value . This option can work whether you want to keep the home or your former partner does. What Is the Spousal Buyout Program? The spousal buyout program is a refinancing option that allows one owner to purchase the other owner’s share of the property as part of a separation or divorce settlement. In some cases, it can also be used to pay off jointly held debts, as outlined in a legal agreement. Below are some of the most common questions about how the program works. Is a finalized separation agreement required? Yes. Lenders require a signed and finalized separation agreement that clearly outlines how assets and debts are to be divided. This document is essential for approval. Can the funds be used for renovations or personal debts? No. Funds from a spousal buyout can only be used to: Buy out the other owner’s share of equity Pay off joint debts specifically listed in the separation agreement They cannot be used for renovations, personal loans, or unrelated expenses. How much equity can be accessed? The maximum amount available is the amount required to: Buy out the other party’s agreed-upon share of equity Pay off any joint debts listed in the agreement This amount cannot exceed 95% loan-to-value . What is the maximum loan-to-value allowed? The maximum loan-to-value is the lesser of : 95%, or The remaining mortgage balance plus the required buyout and joint debt payout The property must be the primary owner-occupied residence . Do all parties need to be on title? Yes. All individuals involved in the buyout must currently be registered on title. Your solicitor will confirm this through a title search. Does this only apply to married or common-law couples? No. While commonly used for married or common-law couples, the program may also apply to siblings or friends who jointly own a property and need one party to exit the mortgage. These cases are typically reviewed on an exception basis and require insurer approval. If no separation agreement exists, the purchase contract must clearly outline the buyout terms. Is a full appraisal required? Yes. A physical, on-site appraisal is required to confirm the property’s value before the mortgage can be finalized. Final Thoughts This overview covers some of the most common questions about mortgage options during separation or divorce, but every situation is different. Working with an independent mortgage professional gives you access to multiple lenders, specialized programs, and unbiased advice—so you can clearly understand your options and choose what’s best for your future. If you’re navigating a separation and need guidance around keeping or selling the home, feel free to connect anytime. All conversations are handled with discretion and confidentiality, and I’d be happy to walk you through your options.
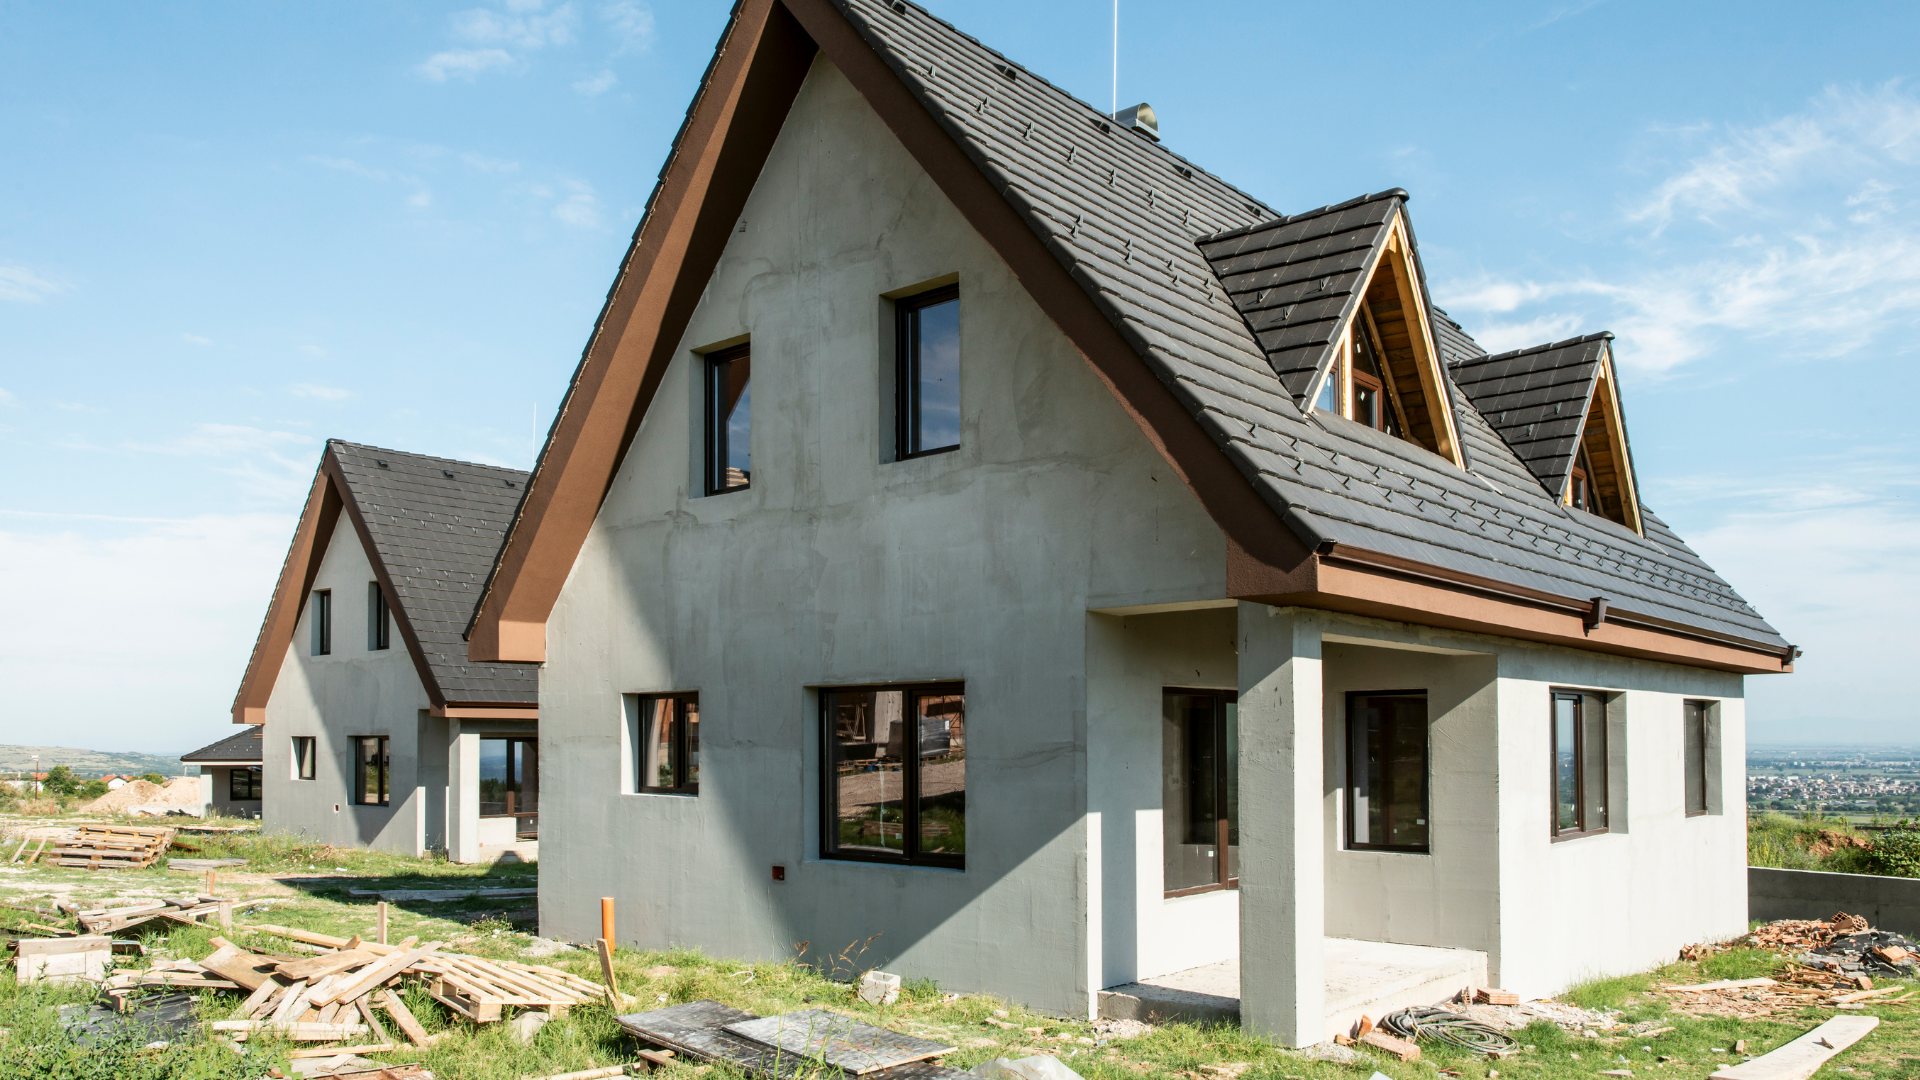
Why More Mortgage Options Matter—Especially for Assignment Purchases One of the biggest advantages of working with an independent mortgage professional is access to choice. Instead of being limited to one lender and one set of products, mortgage brokers work with multiple lenders—each with different guidelines, risk tolerances, and mortgage solutions. That flexibility becomes especially valuable when your situation doesn’t fit neatly into a “standard” box. A great example of this is purchasing new construction through an assignment contract . Why Assignment Purchases Can Be Challenging Assignment purchases are often viewed as higher risk by traditional lenders. Rather than declining these deals outright, many lenders quietly make them difficult by adding layers of conditions, restrictions, or uncertainty. This can lead to delays, frustration, or financing falling apart late in the process. The Good News There are lenders—available exclusively through the broker channel —that have clear, favourable policies for assignment purchases. With the right lender and proper planning, these transactions are absolutely doable. Typical Financing Requirements for Assignment Purchases While every situation is unique, many lenders that allow assignment financing look for the following: Standard purchase qualification, including income verification, credit, and down payment Assignments accepted at either the original purchase price or current market value Minimum 620 credit score , with no prior bankruptcies or consumer proposals The full down payment must come from the purchaser —seller incentives cannot be used Required Documentation To secure financing, lenders typically require: The original purchase agreement signed by all parties The MLS listing (if applicable) The assignment agreement signed by the builder, original purchaser, and new buyer Any side agreements outlining changes to the purchase price A full appraisal to confirm value This list isn’t exhaustive, but it highlights that while assignment purchases require more coordination, they are very achievable with the right lender and guidance. Final Thoughts Assignment contracts can open doors to great opportunities—but only if your financing supports the transaction. This is where access to multiple lenders and specialized policies makes a real difference. If you’re considering purchasing new construction through an assignment, or if you’d like to explore more traditional purchase options, feel free to connect anytime. I’d be happy to walk you through the mortgage products available and help you choose an option that doesn’t limit your financing possibilities.
Stephanie Barritt
Phone: 1-604-575-2710
Ask Steph